The Retirement Income Disconnect: Why Aren’t Retirement Income Solutions Boosting Participant Confidence?
Guest Contributors:
Vivek Amin, Senior Vice President, Wealth and Institutional, Escalent
Sonia Davis, Sr. Product Director, Cogent Syndicated, Escalent
Background:
Helping participants navigate the drawdown years remains one of the defined contribution industry’s most complex challenges. Longer lifespans, rising healthcare costs, market uncertainty and wealth-transfer considerations all add pressure to an already difficult transition: turning accumulated savings into sustainable retirement income.
New data from Cogent Syndicated’s Retirement Planscape and DC Participant Planscape studies point to a notable disconnect. While plan sponsors are increasingly adopting or considering retirement income solutions, participant confidence in converting savings into real-life income remains low.
Findings:
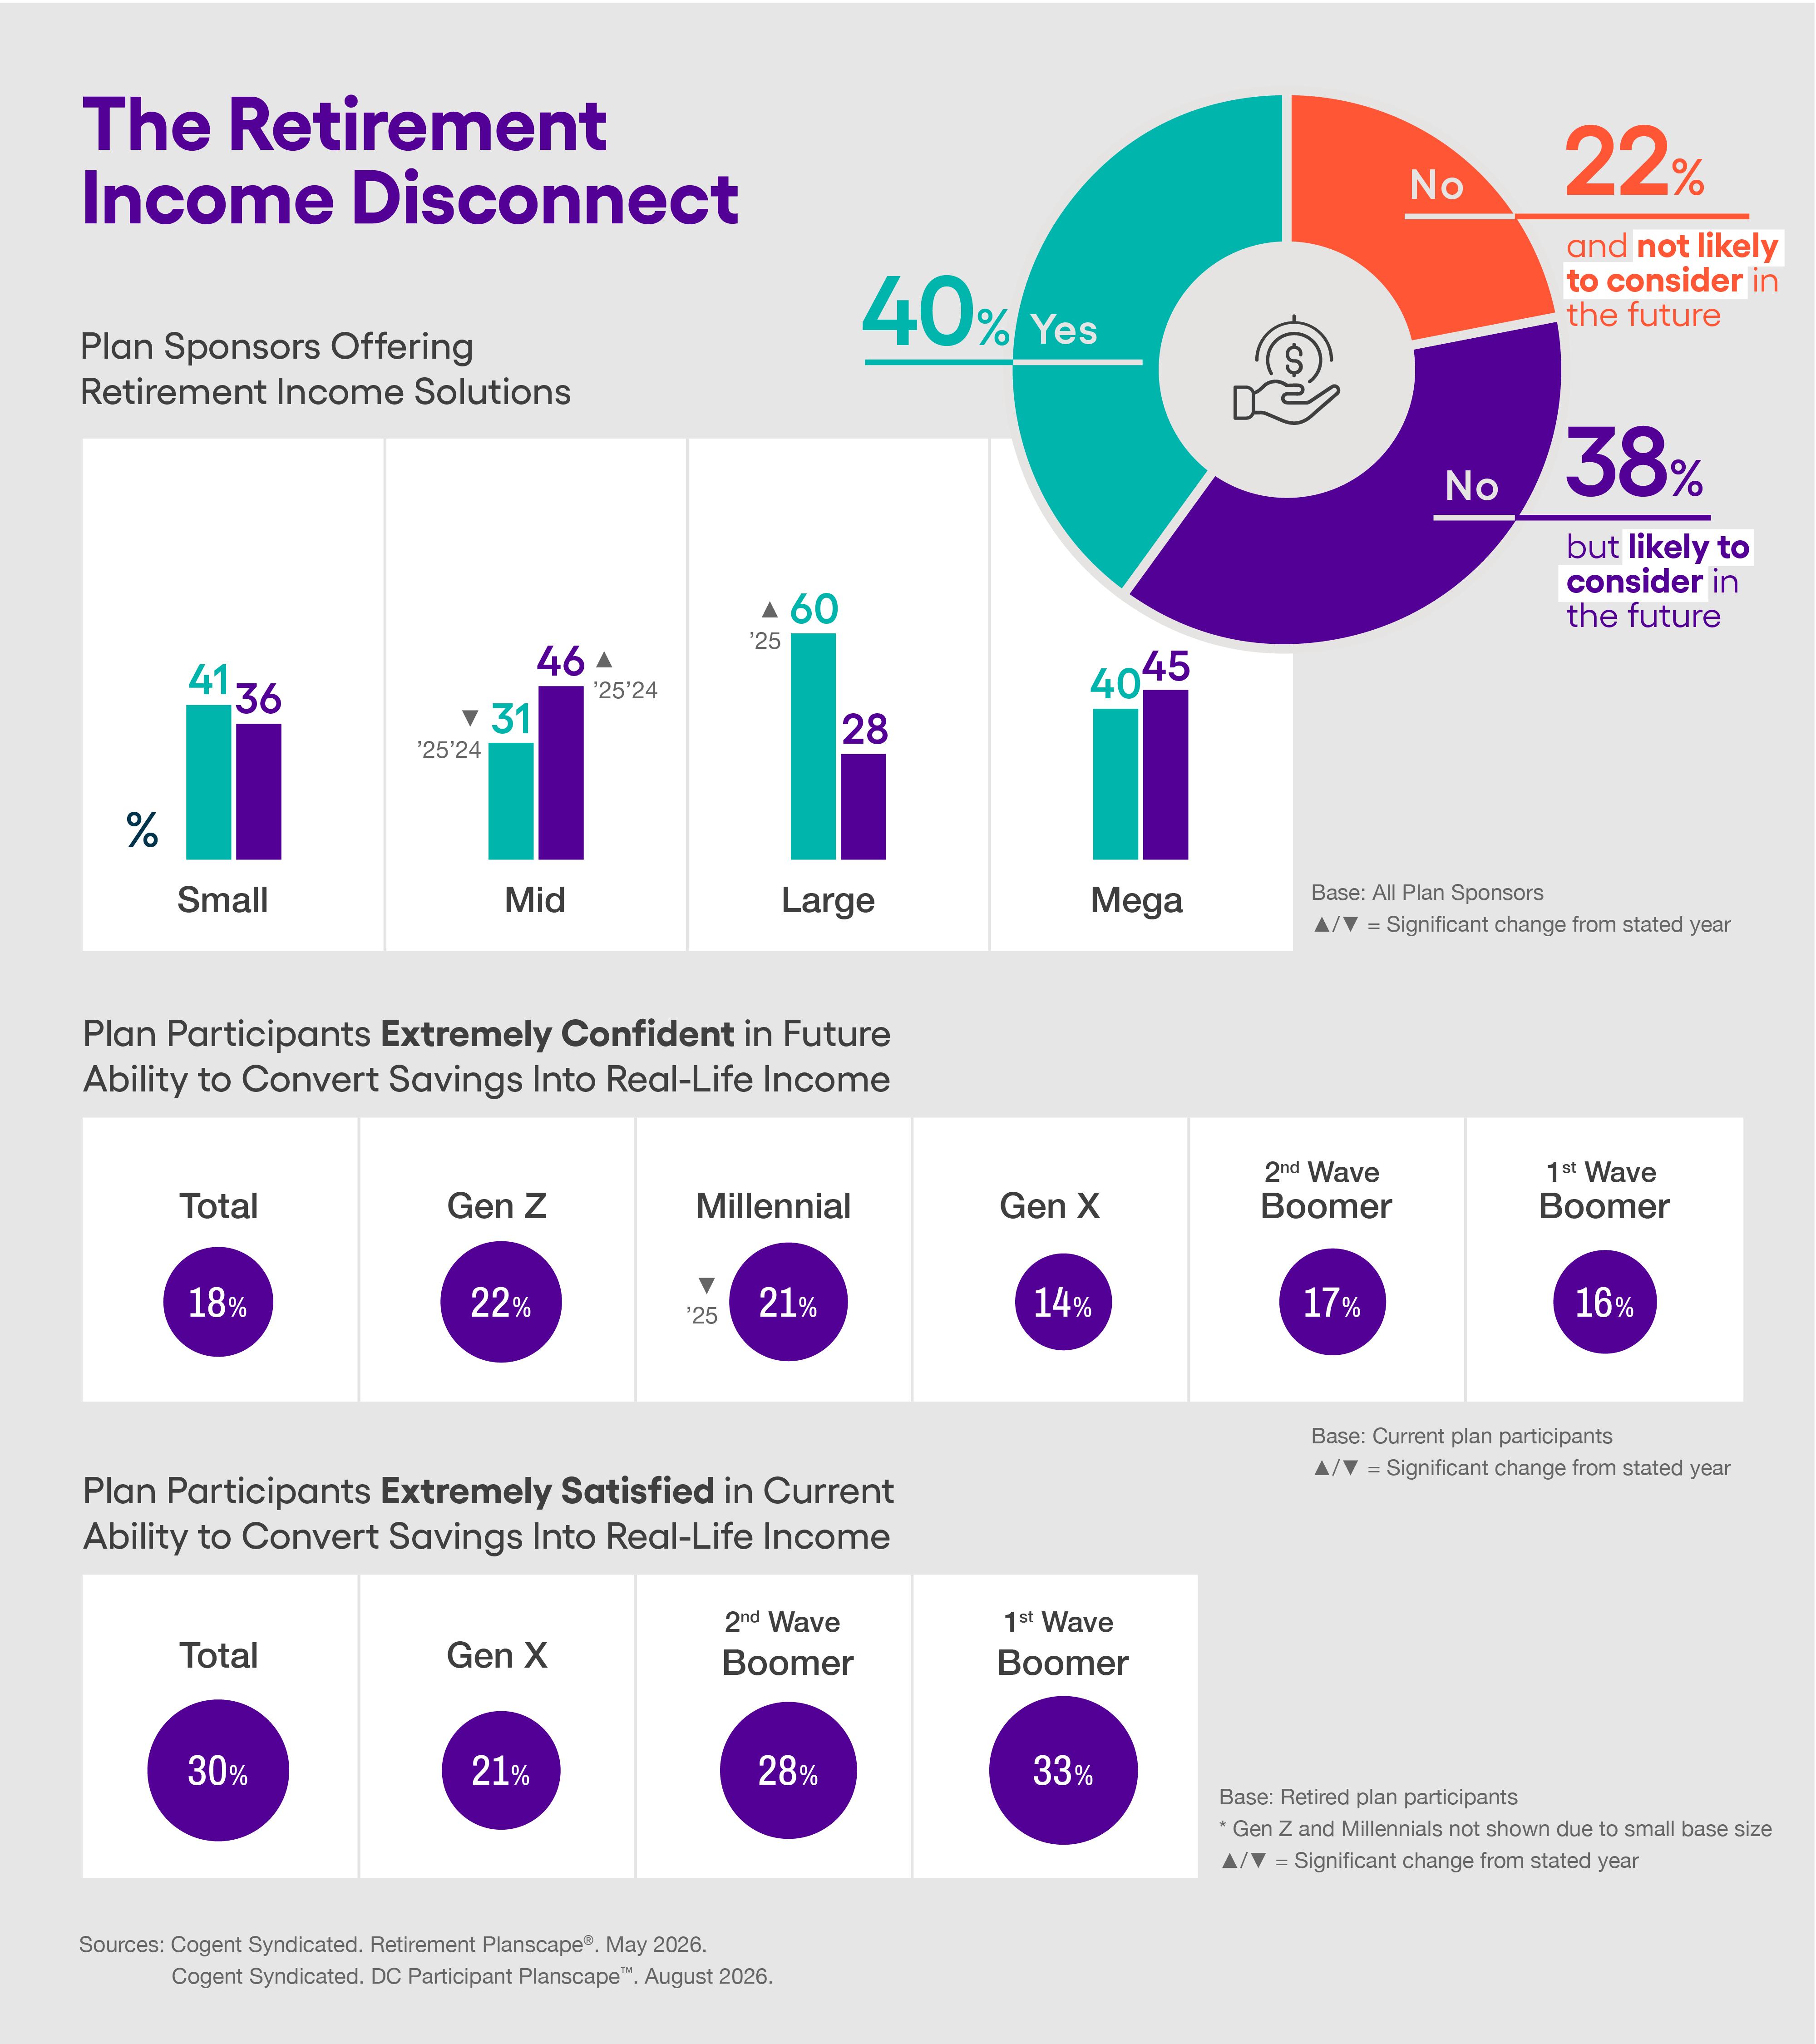
Retirement income solutions continue to gain traction among DC plan sponsors. More than three-quarters of sponsors either currently offer a retirement income solution (40%) or say they are likely to consider one in the future (38%). Adoption is especially strong among large plans ($100M to <$500M), where current offerings increased from 43% to 60% year over year. Among mid-size plans ($20M to <$100M), future intent also rose meaningfully, climbing from 31% to 46%.
Participant sentiment tells a different story. Just 14% of current Gen X participants say they are “extremely confident” in their future ability to convert savings into real-life retirement income. Millennials are only modestly more confident at 21%, down significantly from 27% in the prior year. Even among retired participants, confidence in drawdown execution remains uneven: only 21% of Gen X retirees are “extremely satisfied” with their current ability to convert savings into income, compared with 33% of first Wave Boomers and 28% of second Wave Boomers.
The issue does not appear to be a lack of participant interest. Participants readily acknowledge the need for more help with decumulation decisions. When asked what providers can offer to support the withdrawal planning process, participants most frequently cite help maximizing retirement income (53%), guidance on not outliving savings (45%) and support determining an appropriate withdrawal rate (42%).
For plan sponsors, however, barriers remain. The perception of high fees and expenses (61%), weak participant demand (56%) and fiduciary concerns (45%) continue to be the most significant obstacles to broader retirement income solution adoption.
Bottom line:
The retirement income market is advancing, but participant understanding has not kept pace. The industry’s next challenge may be less about whether retirement income solutions are available and more about whether participants understand, trust and know how to use them.
For providers and plan sponsors, this suggests that product innovation alone will not be enough. Firms that pair retirement income solutions with targeted education, intuitive withdrawal tools and personalized engagement strategies will be better positioned to improve participant confidence and help translate adoption into meaningful retirement outcomes.
---
Insights shared by guest contributors are their own and do not represent the views of DCIIA or the RRC. The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.